Moving From a Condo to a House in Victoria BC | Move-Up Guide
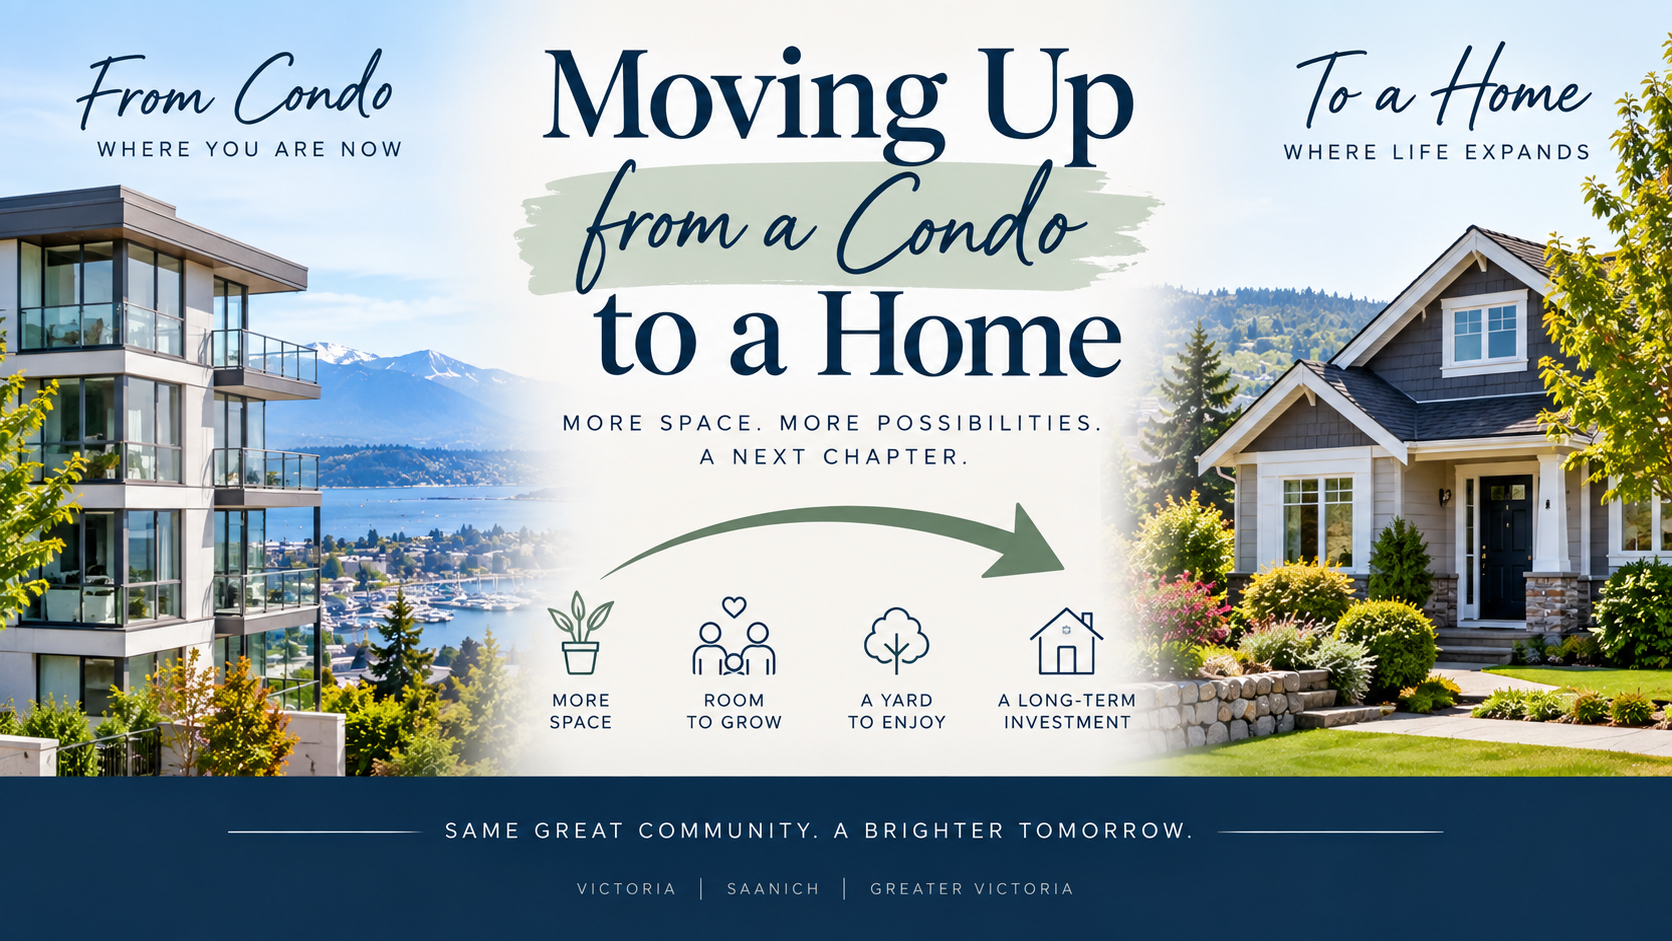
Moving From a Condo to a House in Victoria BC: How to Make the Move Work
Your condo may have been the perfect first home. But eventually, life can start asking for more—another bedroom, a home office, storage, a backyard, room for children or pets, or simply a little more breathing space.
That's when the idea of moving into a house often begins. And then comes the bigger question: How do you sell your condo and buy your next home without making the process unnecessarily stressful?
For move-up buyers in Victoria, the challenge usually isn't simply finding a house. It's coordinating two transactions, understanding how much equity you have available, arranging financing and deciding whether you should sell first or buy first.
You don't need to figure everything out before you start looking. The first step is understanding the value of your current condo, your approximate equity and your borrowing capacity. Once those pieces are clear, we can build the move around real numbers rather than guesswork.
1. Start With Your Current Condo
Before we start seriously looking at houses, I want to understand the property you already own.
What would your condo realistically sell for in today's market? How much is remaining on your mortgage? Are there costs associated with selling? Is there anything we should do to the condo before putting it on the market?
The difference between what your condo may sell for and the amounts that must be paid from the proceeds helps us understand the equity that may be available for your next purchase.
This is why I prefer to begin a move-up conversation with a market analysis of the current home rather than immediately sending buyers listings for houses.
2. How Much Equity Do You Have?
For many homeowners, the equity accumulated in their condo becomes an important part of the down payment on their next property.
A simple way to begin estimating that equity is:
− Mortgage Balance
− Selling & Closing Costs
= Approximate Available Equity
This is only a planning calculation. Your actual net proceeds will depend on your mortgage, legal costs, real estate costs, adjustments and other property-specific expenses.
But having a realistic estimate gives us a much better starting point for determining what the next move could look like.
3. Find Out What You Can Comfortably Afford
The next step is usually a conversation with your mortgage professional.
The question isn't simply, "What's the maximum amount the bank will lend me?" I think a more useful question is:
What purchase price gives me the home I want while still leaving me comfortable with my monthly costs?
A house may come with expenses you didn't have—or had less direct exposure to—in a condo. Heating, insurance, utilities, exterior maintenance, landscaping, roof replacement and other repairs now fall directly to you.
Understanding the complete cost of the move helps you choose a home that fits both your lifestyle and your finances.
4. Should You Sell Your Condo First or Buy the House First?
This is usually the biggest question for a move-up buyer.
There isn't one answer that works for everyone. The right strategy depends on your finances, your tolerance for uncertainty, the market for your condo and how difficult your next home may be to find.
Selling First
Selling first gives you more certainty. You know what your condo sold for and therefore have a much clearer understanding of the funds available for your purchase.
It can also put you in a stronger position when writing an offer because your purchase may not need to depend on selling your existing property.
The trade-off is timing. If you haven't found your next home by the time your condo completes, you may need temporary accommodation or another short-term solution.
Buying First
Buying first can make sense when the right house is difficult to find or when you have enough financial flexibility to manage the transition.
But it can also create more risk. You need to understand what happens if your condo takes longer to sell than expected or sells for less than anticipated.
Your REALTOR® and mortgage professional should help you understand those scenarios before you commit to the new purchase.
5. Can You Make Your Purchase Subject to Selling Your Condo?
In some circumstances, a buyer may write an offer that is conditional on selling their existing property.
Whether that strategy is practical depends heavily on current market conditions and the individual property. A seller considering several offers may prefer an offer without a sale-of-property condition, while another seller may be willing to consider one.
This is where understanding the market becomes particularly important. The strategy that makes sense in a slower market may be very different from the strategy we would use when desirable houses are receiving significant competition.
6. Don't Forget About the Deposit
This catches some move-up buyers by surprise.
The equity in your condo may ultimately fund much of your down payment, but that doesn't necessarily mean those funds are available when the deposit on your new purchase becomes due.
If your condo sale hasn't completed yet, you may need another source for the deposit.
Talk to your mortgage professional about where your purchase deposit and eventual down payment will come from before writing an offer. The timing of available funds matters just as much as the amount.
7. What About Bridge Financing?
Sometimes the completion date for your new house arrives before the completion date for your condo sale.
Depending on your circumstances and lender, bridge financing may be one tool that helps cover a short timing gap between the two transactions.
Bridge financing isn't automatic and isn't appropriate for everyone. Eligibility, cost and requirements vary by lender, so this needs to be discussed with your mortgage professional before completion dates are finalized.
8. What Do You Actually Need From the House?
Once the financial framework is clear, we can turn our attention to the fun part: what does your next home need to do for you?
Instead of starting with a long list of finishes and features, I like to understand why you're moving.
Do you need another bedroom?
A larger backyard?
A home office?
More storage?
A better school location?
A quieter street?
Space for aging parents?
A garage or workshop?
A shorter commute?
Those answers help us separate the things that are easy to change from the things that aren't.
9. A House Requires Different Due Diligence Than a Condo
Moving from a condo into a detached home introduces a different level of property due diligence.
In a condo, the strata is typically responsible for many common-property components. With a detached home, you'll be looking much more closely at the roof, drainage, sewer line, electrical system, plumbing, heating, windows, foundation, exterior and property itself.
Older Victoria homes may also raise questions about permits, oil tanks, asbestos-containing materials, perimeter drains, sewer laterals, water service lines and previous renovations.
10. Location Matters Even More Than the House
One of the easiest mistakes to make when moving up is becoming so excited about getting more space that you compromise too much on location.
Kitchens can be renovated. Flooring can be changed. Walls can sometimes be moved.
You can't move the property away from a busy road, shorten the commute or give the lot a better orientation.
This is why I encourage move-up buyers to compare neighbourhoods as carefully as they compare houses.
Your Move-Up Roadmap
Step 1: Determine the realistic market value of your condo.
Step 2: Estimate your available equity and selling costs.
Step 3: Meet with your mortgage professional and establish a comfortable purchase range.
Step 4: Decide whether selling first or buying first makes the most sense.
Step 5: Define what your next home actually needs to provide.
Step 6: Begin watching both the condo market and the market for your next home.
Step 7: Coordinate the sale, purchase, conditions and completion dates strategically.
You Don't Have to Be Ready to Move Tomorrow
Some of my best conversations with move-up buyers happen months before they're ready to do anything. That's actually an ideal time to talk. We can look at what your condo may be worth, what houses in the neighbourhoods you're considering are selling for and what needs to happen financially to bridge the gap. There is no pressure to put a sign on your condo. The goal is simply to give you enough information to know whether moving up makes sense—and, if it does, to have a plan before the right house comes along.
Frequently Asked Questions
Should I sell my condo before buying a house in Victoria BC?
It depends on your financial position, the market for your condo, how difficult your next property may be to find and your comfort with risk. Selling first provides greater certainty, while buying first may provide more flexibility when searching for a hard-to-find home.
Can I use the equity in my condo as the down payment on a house?
Equity from the sale of your condo may form part of the funds used toward your next purchase. The amount and timing should be reviewed with your mortgage professional because your condo sale proceeds may not be available when an earlier purchase deposit is required.
Can I buy a house before my condo sale completes?
Potentially. Whether this is financially possible depends on your financing, available funds, lender requirements and the timing of both transactions. Your mortgage professional should review the proposed structure before you commit to a purchase.
What is bridge financing?
Bridge financing is short-term financing that may be available in certain circumstances when a buyer's new purchase completes before the sale of their existing home. Availability, qualifications and costs depend on the lender and the buyer's circumstances.
How do I know what my condo is worth?
A REALTOR® can prepare a comparative market analysis using recent sales, competing listings and the specific characteristics of your building and unit. This provides a useful starting point for planning your next purchase.
When should I start planning a move from my condo to a house?
You can begin well before you're ready to sell. Understanding your condo's approximate value, your financing options and the cost of homes that meet your needs can help you decide whether moving up is realistic and prepare for the right opportunity.
Wondering If You're Ready to Move Up?
We can start with a simple conversation about your condo, your approximate equity and what you're hoping to find next. You don't need to be ready to list your home to start planning.
Talk With Dawn
Categories
Recent Posts