Low Home Appraisal in Victoria BC: What Buyers Need to Know
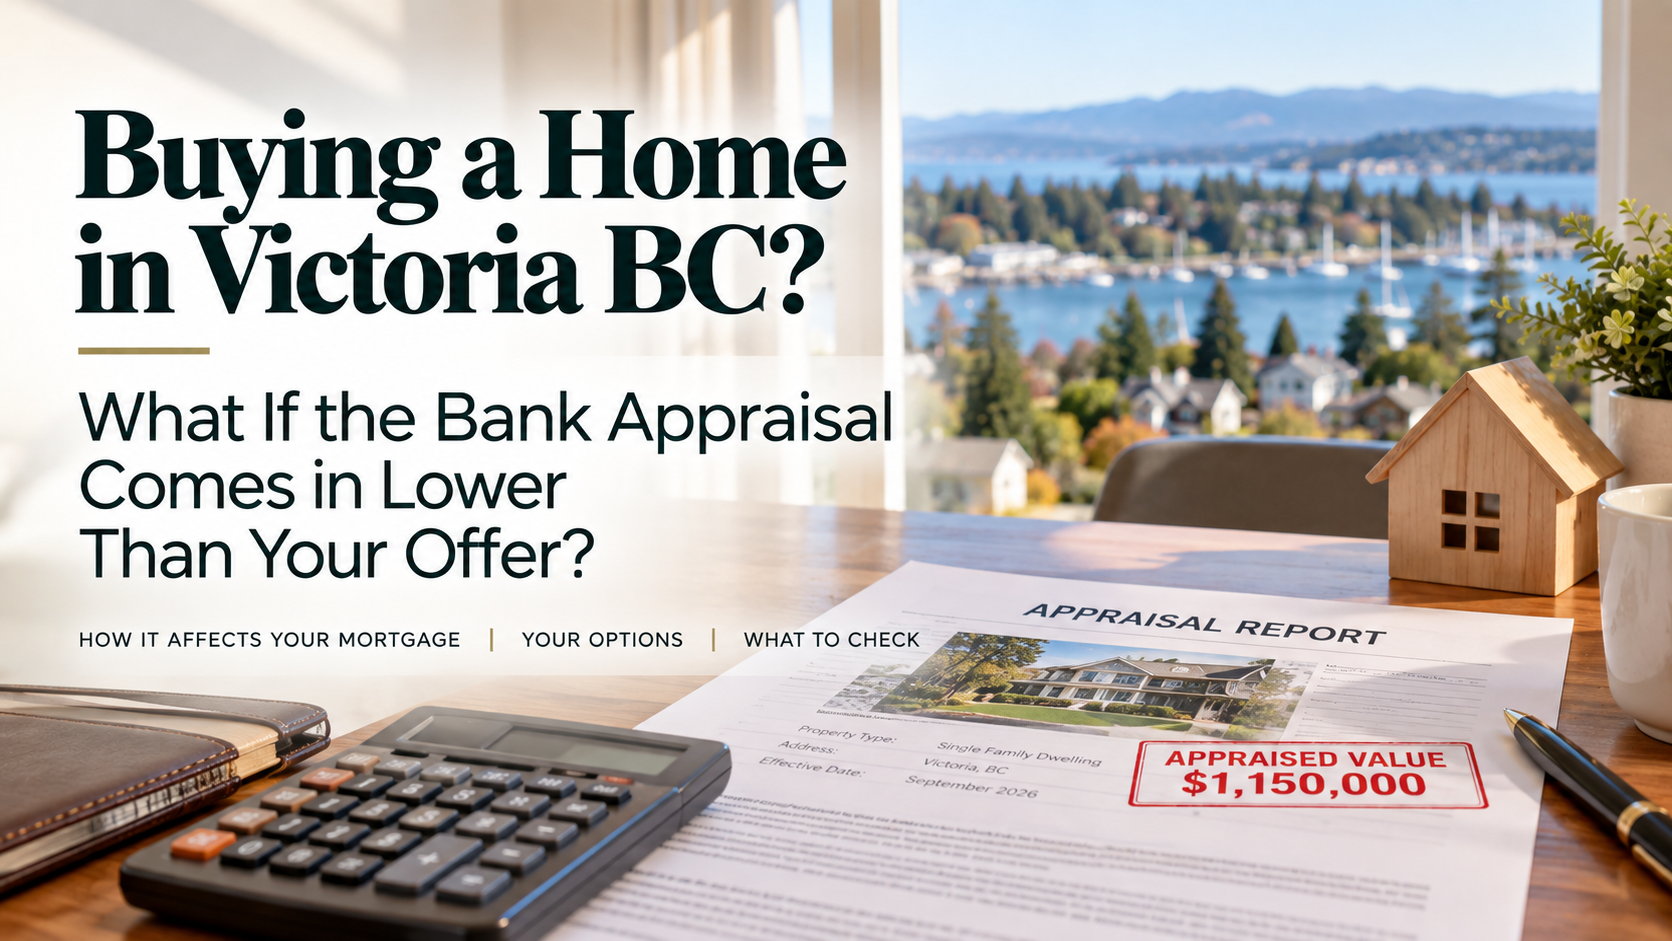
Victoria BC Home Appraisal: What If It Comes in Lower Than Your Offer?
You've found a home in Victoria that you love. Your offer is accepted, you've been pre-approved for your mortgage, and you're working through your purchase conditions.
Then your lender orders an appraisal.
You agreed to pay $1,200,000 for the home, but the lender's appraisal comes in at $1,150,000.
Now what?
Does the lender still finance the purchase? Do you need to come up with another $50,000? Can the appraisal be reviewed? Can the purchase price be renegotiated?
These are important questions because a mortgage pre-approval does not necessarily mean that a lender has approved the particular property you're buying at the price you've offered.
What Is a Home Appraisal?
A home appraisal is an independent opinion of a property's value prepared by a qualified appraiser.
A mortgage lender may require an appraisal as part of its financing process because the property itself is security for the mortgage.
The appraiser may consider factors such as the home's location, size, condition, features and recent comparable sales.
The important point for buyers is that the appraisal is being completed for the lender's financing purposes. It isn't simply confirmation of the price you and the seller agreed upon.
Why Can a Victoria Home Appraise Below the Offer Price?
There are several reasons an appraisal and an accepted offer might not arrive at exactly the same value.
Sometimes buyers are competing for a particularly desirable property and agree to pay more than recent comparable sales suggest.
In other cases, the house may be difficult to compare.
Greater Victoria has many neighbourhoods where two houses on the same street can be very different.
A property may have:
- An extensively renovated interior
- A larger-than-typical lot
- Ocean or mountain views
- A secondary suite
- Unique architecture or character features
- Significant landscaping or outdoor improvements
- A location that is difficult to compare directly with recent sales
That can be particularly relevant in areas such as Gordon Head, Cordova Bay, Cadboro Bay, Oak Bay and Fairfield, where properties can vary considerably even within a relatively small geographic area.
Mortgage Pre-Approval Doesn't Guarantee Approval of the Property
This is something I want buyers to understand early in their home search.
A mortgage pre-approval generally looks at you as the borrower — your income, debts, credit and potential borrowing capacity.
But once you have an accepted offer, the lender also needs to be satisfied with the property being used as security for the mortgage.
"I can afford the monthly payment" and "the lender will finance this property at this price" are not necessarily the same thing.
That's one reason the financing condition in a purchase contract can be so important.
I don't want the first conversation about appraisal risk to happen after my buyer has already written a very aggressive offer.
Before we write, I look at the recent comparable sales, competing properties, condition of the home, location and anything unusual about the property that may affect value.
That doesn't mean I can predict exactly what a lender's appraiser will conclude. I can't.
My role is to help my buyer understand the market evidence behind the price they're considering and make sure financing and appraisal questions are addressed with their mortgage professional before they make a major commitment.
What Happens If the Appraisal Comes in Low?
Let's return to our example.
Accepted purchase price: $1,200,000
Lender's appraised value: $1,150,000
Difference: $50,000
A low appraisal does not automatically mean that the buyer simply writes a cheque for the entire difference.
The actual impact depends on the buyer's financing structure, down payment, lender requirements and mortgage program.
That's why the first call should be to the buyer's mortgage professional.
1. Find Out Exactly How the Appraisal Affects Your Financing
Before reacting to the appraisal number, I want the buyer to understand what it actually means for their mortgage.
Their mortgage broker or lender can explain whether the lower value changes the amount the lender is prepared to advance and whether the buyer's planned down payment is affected.
Until we have that information, we don't really know the size of the problem — or whether there is a significant problem at all.
2. Review the Comparable Sales
If the appraisal comes in below the purchase price, one of the things I can do as the buyer's REALTOR® is revisit the market evidence.
Were there recent comparable sales that support the purchase price?
Is there something about the subject property that may not have been fully reflected in the appraisal?
Are the properties used as comparables genuinely similar?
This doesn't mean we simply disagree with an appraisal because we don't like the number. It means we look carefully at the available evidence.
3. Can an Appraisal Be Reconsidered?
Depending on the lender and circumstances, there may be a process for providing additional relevant information for consideration.
For example, there may be a recent comparable sale or a material property feature that deserves attention.
That doesn't guarantee the appraised value will change.
The appropriate process should be discussed with the mortgage professional or lender rather than assuming an appraisal can simply be "challenged."
4. Understand How Much Additional Cash You Might Need
If the lender will not support the purchase at the expected financing level, the buyer may need to determine whether additional funds are required to complete the purchase.
Again, the amount isn't necessarily identical to the difference between the purchase price and appraised value.
Your mortgage professional should calculate the impact based on your particular financing.
5. Can the Purchase Price Be Renegotiated?
Buyers sometimes assume that if the appraisal is low, the seller must reduce the price.
That's not necessarily the case.
The seller and buyer have already agreed to a purchase price, and what happens next depends on the contract, the conditions that remain in place and whether the parties are willing to negotiate.
If a financing condition is still in place and financing cannot be obtained on satisfactory terms, the buyer should obtain appropriate professional advice about their contractual options before taking further action.
Why the Financing Subject Matters
In a competitive market, buyers sometimes feel pressure to remove conditions or write subject-free offers.
That can introduce significant risk.
Even a financially strong buyer can encounter an unexpected property-specific financing issue.
An appraisal is one example.
Before a buyer considers removing or waiving a financing condition, I want them to have a very clear conversation with their mortgage professional about what has — and has not — been approved.
Appraisal Risk Can Matter More With Unique Victoria Homes
Appraisals rely in part on comparable market evidence, and some Victoria properties are simply easier to compare than others.
A relatively standard home in a neighbourhood with several recent similar sales may provide more obvious comparable evidence.
A extensively renovated character home in Fairfield, an ocean-view property in Cordova Bay, a large-lot home in Gordon Head or a distinctive Oak Bay property may have fewer directly comparable recent sales.
That doesn't mean these homes will appraise low. It means buyers should understand that unique properties can require more judgment when establishing value.
What About Sellers?
Appraisal risk isn't only a buyer issue.
Imagine receiving two offers on your Victoria home.
One has the highest price, but the buyer is stretching their financing and has a relatively small down payment.
Another offer may be slightly different in price but have different financing circumstances and conditions.
Price is obviously important, but it isn't the only part of an offer that deserves consideration.
As a seller's REALTOR®, part of my job is helping sellers understand the terms and conditions of each offer so they can evaluate the entire proposal rather than focusing only on the largest number at the top of the contract.
My Appraisal Checklist for Victoria Home Buyers
✓ Has my lender fully reviewed the property?
✓ Is an appraisal required?
✓ Will the appraisal be completed before my financing condition expires?
✓ Have we reviewed recent comparable sales before writing the offer?
✓ Am I offering significantly above recent comparable sales?
✓ Is this property unusual or difficult to compare?
✓ What happens to my financing if the appraisal is lower than my offer?
✓ Could I provide additional funds if required?
✓ Have I discussed appraisal risk with my mortgage professional?
✓ Am I satisfied with my financing before removing my financing condition?
Frequently Asked Questions
Can a home appraisal come in lower than my offer?
Yes. The price a buyer and seller agree upon and the value determined by a lender's appraisal are not necessarily the same. Market conditions, comparable sales, property characteristics and other factors can result in a different appraised value.
Does mortgage pre-approval guarantee financing for the home I buy?
No. A mortgage pre-approval does not necessarily constitute final approval of a specific property. The lender may still need to review the property, appraisal and other information before confirming financing.
Do I have to pay the entire difference if the appraisal is low?
Not necessarily. The financial impact depends on your mortgage structure, down payment and lender requirements. Your mortgage professional can explain how the appraised value affects your particular financing.
Can a low home appraisal be challenged?
Depending on the lender and circumstances, there may be a process for providing relevant additional information or comparable sales for consideration. Buyers should discuss the appropriate process with their mortgage professional or lender.
Does the seller have to lower the price if the appraisal is low?
Not automatically. The buyer and seller have already agreed to a purchase price. What happens next depends on the purchase contract, any remaining conditions and whether the parties agree to further negotiations.
Should I remove my financing subject before the appraisal is complete?
Buyers should understand exactly what their lender has approved before removing a financing condition. If an appraisal is required but has not yet been completed, the buyer should discuss the potential risk with their mortgage professional and obtain appropriate professional advice before making a decision.
Helpful BC Home Buyer Resources
- BC Financial Services Authority — Buying a Home
- BCFSA — Should I Make a Subject-Free Offer?
- Canada Mortgage and Housing Corporation — Home Buying Resources
Planning to Buy a Home in Victoria?
A strong offer isn't just about choosing a price. I help my buyers understand the comparable sales, market conditions, property-specific risks and due-diligence steps behind their decision so they can move forward with greater clarity and confidence.
Explore Victoria Real Estate with DawnDawn Stokkeland | REALTOR®
eXp Realty
Serving Victoria, Saanich, Gordon Head, Cordova Bay, Cadboro Bay, Oak Bay, Fairfield, Fernwood, Esquimalt, Royal Oak, Sidney and Greater Victoria.
Categories
Recent Posts